fintech IRELAND
email / social
  • Home
  • Fintech Authorisations
  • Fintech Education & Training
  • Fintech Ireland Map
    • Fintech Survey
  • Events
    • Summit
    • Events-Archive
  • Fintech Hub
  • News-Insights
    • Consultations
    • News Page Back Up
  • Careers
  • RegTech
  • CRYPTO
  • Fundraising
  • Brexit & Ireland
  • About
    • Fintech Family Network
  • Get Involved

Ireland’s VASPs holding their own against the UK? The Virtual Asset Service Providers Landscape in Ireland

12/4/2023

0 Comments

 
Picture
This article is co-authored by Susan O’Neill of SuLu Solutions and Peter Oakes of Fintech Ireland*.

17 July 2023 - find New Version of this Registered Virtual Asset Service Providers Map, V 2.0 HERE

[Updated on 12 April 2023 to add Kraken to the article which appear on the VASP register today]


Ireland has a small number of registered Virtual Asset Service Providers (VASPs). In Ireland it is a criminal offence to carry on the business of a VASP in the absence of registration from the Central Bank of Ireland (CBI). VASPs came within the scope of Ireland’s Anti-Money Laundering (AML)/Countering Financing of Terrorism (CFT) legislation in April 2021.  As per the CBI Anti-Money Laundering Bulletin issued on 8 July 2022 (CBI AML Bulletin), “In the intervening period, a significant number of firms have applied to the Central Bank for registration.”

If a significant number of firms have applied to be registered as VASPs – the question arises as to: “Why, 2 years later, Ireland has issued only six (6) VASPs?” This begs further questions: Is Ireland behind the curve compared to its international peers? Are the firms applying in Ireland sufficiently resourced to become VASPs? How do we, more specifically, compare to our neighbours in the UK?
​
If a significant number of firms have applied to be registered as VASPs – the question arises as to: “Why, 2 years later, Ireland has issued only six (6) VASPs?”
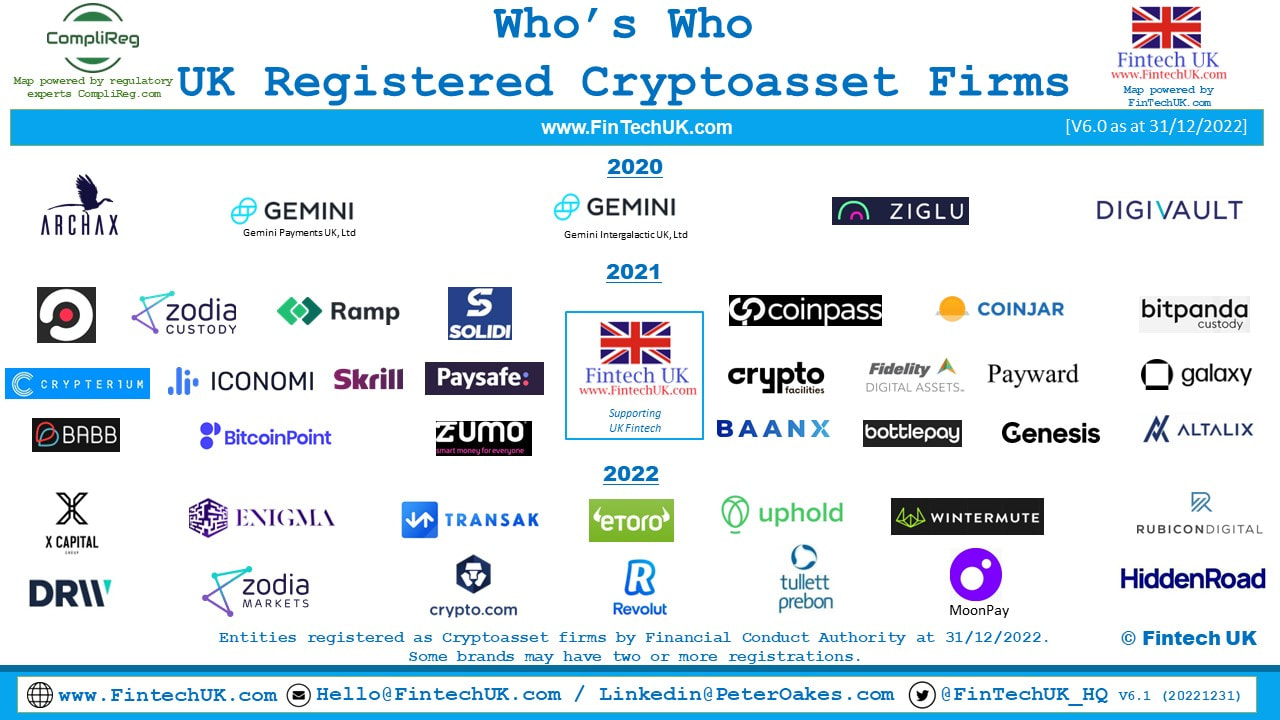
​Of the six (6) registered VASPs –two of the registrations are held by Coinbase. The UK has 41 cryptoasset firms registered with the Financial Conduct Authority (FCA). The FCA also have a list of 82 unregistered cryptoasset businesses (as at 31 March 2023), down from close to 250 during 2022, but perhaps this is a topic that deserves an article all of its own!

The UK has 41 cryptoasset firms registered with the Financial Conduct Authority
Picture
Check out Fintech UK's most recent edition of its famous UK Registered Cryptoasset Firms Map
The UK’s population is 13 times larger than that of Ireland (UK 67.33mn versus Ireland 5.033mn according to World Bank, Eurostat 2021 figures). Accordingly, the UK has one registered cryptoasset firm for every 1.64mn persons.  Whereas for Ireland it is one crypto firm for every 838,833 persons.  By that comparison, Ireland has more crypto firms per head of population than the UK. Based on those numbers Ireland is not only holding its own vis-à-vis the UK, it is exceeding it by a large margin.  If Ireland registered say another 9 VASPs (to get it to 15 VASPs) it would have one cryptoasset firm for every 335,500 persons. Is this something that policymakers, the government and the CBI take into account as part of their respective cryptoasset strategies? 
Ireland is not only holding its own vis-à-vis the UK, it is exceeding it by a large margin.
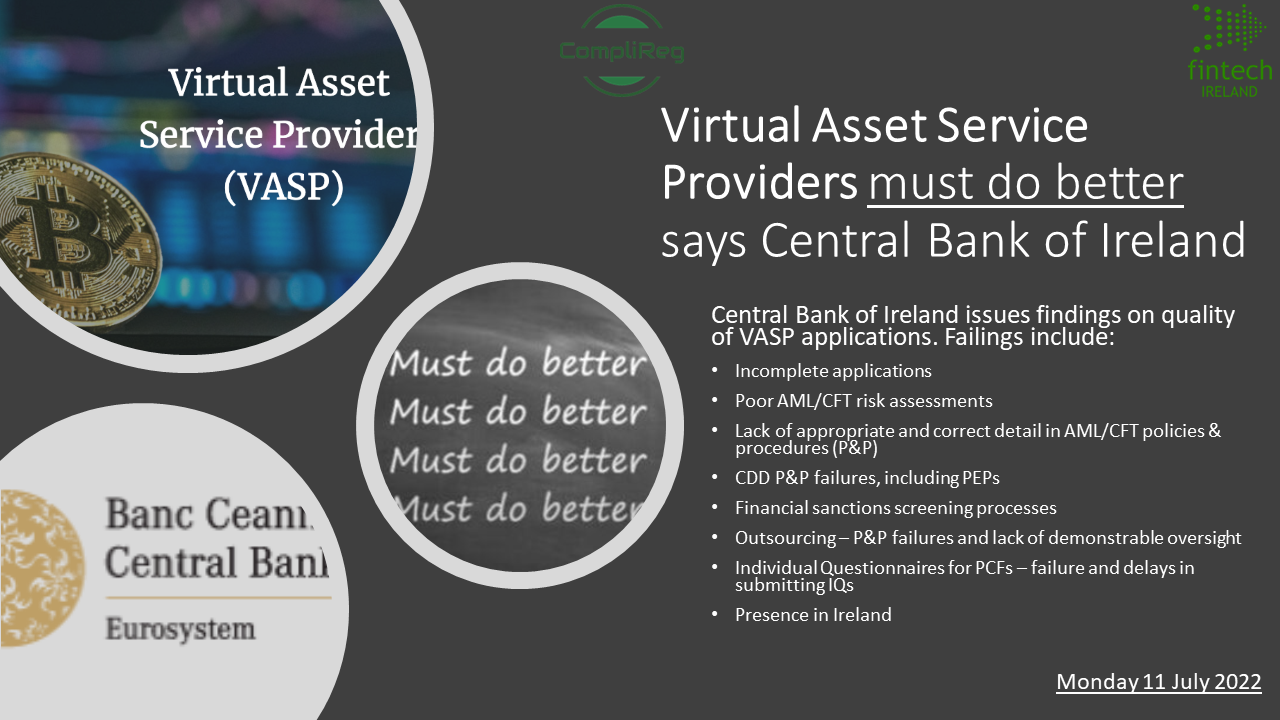
The CBI AML Bulletin noted the following “In its assessments of applications for registration as a VASP, the Central Bank has identified significant and widespread weaknesses in the proposed risk and control frameworks of the vast majority of applicants. These weaknesses are such that the Central Bank is not satisfied that firms will have the necessary and appropriate controls in place to effectively manage and mitigate the ML/TF risk to the firm, the sector and society.”


Widespread weaknesses in “the vast majority of applicants” does not inspire confidence in the future of VASP applicants in Ireland. However, it is relevant to note that the FCA too has, as recently as 22 March 2023, criticised the quality of cryptoasset applications received by it, particular in areas relating to business plans, comprehensive description of products and services, risk assessment, risk management, policies, systems & controls, Transaction monitoring and blockchain analysis coverage, Group structure and reliance on group policies and procedures, Outsourcing, Training, Suspicious Activity Reporting and regulatory disclosures.  The FCA reminded crypto asset firms of its concerns on 5 April 2023 (see below).

​So, what can be done to support applicants, and thereby improve applications? There is no doubt that the crypto industry is going through the growing pains of a market that needs regulation, but regulation needs to put the guard rails in place to support its users, while also ensuring it does not stifle innovation. There is a very real opportunity here to ensure that Ireland is at the forefront of positive regulatory changes – Ireland could become a hub for the crypto ecosystem.  There are already a number of very large players based in Dublin.  In the same breath, the cryptoasset firms and VASPs referred to in this article are themselves not ‘regulated’ but are merely registered for the purposes of anti-money laundering and terrorist financing laws, i.e. VASPs and cryptoasset firms in Ireland and the UK are not authorised.  However some such firms have a separate authorisation, for example Archax, which is both a registered cryptoasset firm and a UK authorised investment services firm and multi-lateral trading facility, subject to extensive conduct and prudential rule books.  As the crypto industry continues to mature, expect to see numerous ‘digital asset’ firms seek to differentiate and distance themselves from the speculative trading and exchange-driven cryptoasset firms which are falling under evermore regulatory scrutiny such as Binance, Coinbase and Kraken and the failed FTX and Genesis Trading (both of which have filed for bankruptcy protection in the US).
​
There is no doubt that the crypto industry is going through the growing pains of a market that needs regulation, but regulation needs to put the guard rails in place to support its users
​In order to address some of the concerns noted above, the European Union’s trailblazing Markets in Crypto-Assets (MiCA) Regulation is set to come into effect across all member states in 2024, but will it be enough? Dubai’s Virtual Asset Regulatory Authority is the world’s first independent regulator for virtual assets.  Dubai is fast becoming a hub for the crypto ecosystem. Could Ireland benefit from a similar initiative? This is highly unlikely as Ireland traditionally follows the EU’s lead on new financial services regulations and there has been nothing issued by the Department of Finance to suggest that this time is different.  In April 2022 the UK Government announced its plans to make the UK “a global cryptoasset technology hub”. The UK government intends to bring stablecoins into the regulatory perimeter and has launched a consultation on the country’s proposed central bank digital currency or ‘digital pound’ as it is called.  The UK also caught many in the industry unawares when on 31 January 2023, without warning, it published a consultation on the Future financial services regulatory regime for cryptoassets.
​

Who are the Super Six of Irish Crypto?
​

​So, who are the companies that have managed to obtain the elusive Irish VASP registration and what services are they registered to provide?
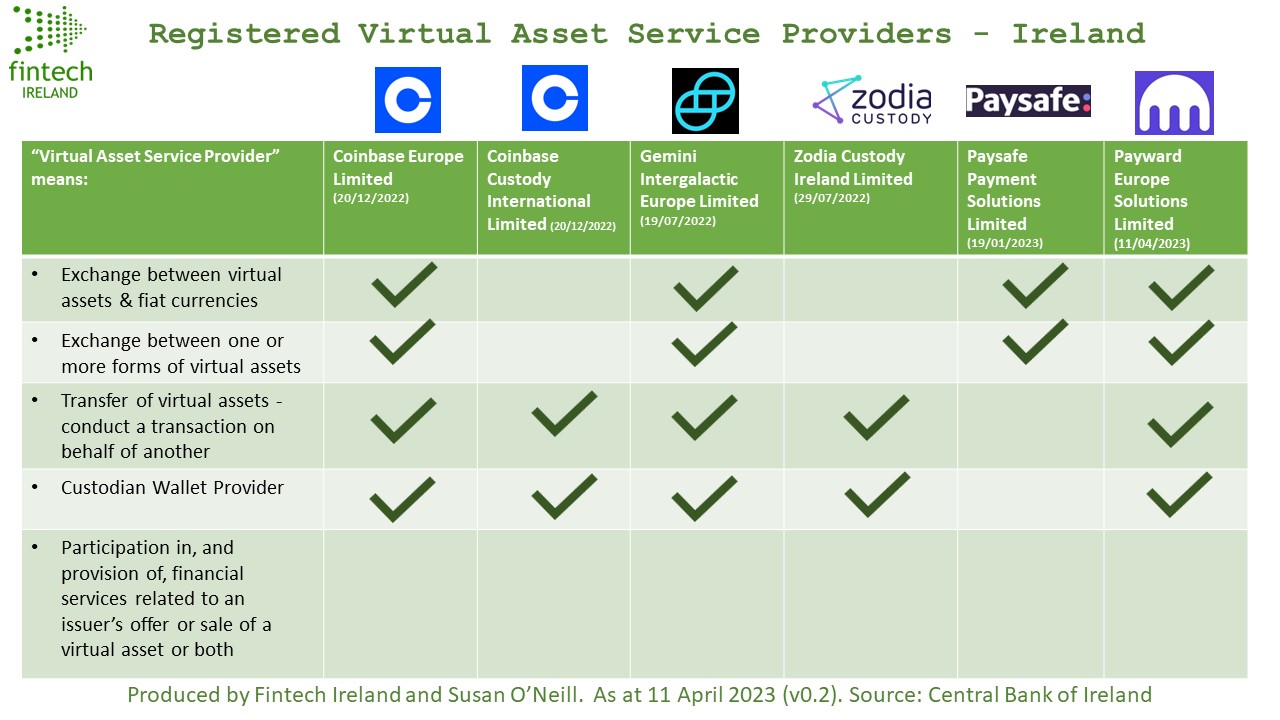
​The first registered VASP in Ireland was Gemini Intergalactic Europe Limited, registered on 19 July 2022 under its then name Gemini Digital Assets Limited. Next up was Zodia Custody Ireland Limited, registered on 29 July 2022, followed by both Coinbase Custody International Limited and Coinbase Europe Limited on 20 December 2022.  Paysafe Payment Solutions Limited joined these with a registration date of 19 January 2023.  The most recent VASP to appear on the CBI’s register is Payward Europe Solutions Limited (aka Kraken) whose registration appeared on 11 April 2023.

What services can VASPs offer? 

The services these VASPs are registered to provide is summarised in the table below.
Picture
​In recent months, many similarities have been drawn between the current crypto bear market and the dot com crash.  Many wrote off the collapse of US-based Silvergate Bank and Silicon Valley Bank as being completely different from previous financial crises.  However the failure of Credit Suisse - at one point in history the eighth-biggest publicly owned bank by market capitalisation - is making people wonder whether we are seeing the start of a financial crisis like that of 2008.  Increased regulatory scrutiny in the US continues to put pressure on the entire crypto market, regulators recently closed Signature Bank. Signature Bank and Silvergate Bank were widely used by crypto companies. With so much uncertainty there has never been a greater need for carefully considered regulation that will give crypto companies (and their banks) the clarity they need to operate in a compliant regulatory environment. There are many uphill battles ahead for the crypto ecosystem, only the strongest crypto firms will emerge successfully from this bear market. It will be interesting to see which VASP will appear next on the CBI’s register- watch this space!

The Central Bank of Ireland’s Governor’s recent comments on crypto – 25 January 2023

​There was widespread reporting in Irish and international media about comments made by Gabriel Makhlouf, the Governor of the Central Bank of Ireland during his appearance before a committee of Dail Eireann (lower house) in the Oireachtas (Irish Parliament) earlier this year.  Reuters reported that Mr Makhlouf urged lawmakers on to ban the advertising of crypto assets targeted at young adults and likened crypto not linked to any underlying assets to a Ponzi scheme saying “Unbacked crypto is essentially a Ponzi scheme... People who put their money into unbacked crypo, and most of the significant stock of crypto out there is unbacked, they are essentially gambling.”  Coindesk headlined with “the Governor Gabriel Makhlouf said crypto has ‘no social value whatsoever’”.  Whereas Bloomberg wrote “Makhlouf ‘Very Concerned’ About Crypto”.  
Picture
  • I would be grateful if customers could be warned in a very effective way as to the blatant risks of getting involved in crypto currencies in stark red letters: Governor Gabriel Makhlouf
​What did Governor Makhlouf actually say on 25 January this year?  You can read his comments before the Joint Committee on Finance, Public Expenditure and Reform, and Taoiseach here, where ‘crypto’ received 50 mentions during the exchange with members of the Oireachtas, including:
  • My views on crypto have developed. It is important to be clear because we all use the word "crypto" to mean certain things but there is a spectrum of things under that heading. At one end is what I would call unbacked crypto, which is crypto that has no link to any underlying assets and has no anchor to provide stability of value. It asserts that it is money but it is not a unit of account. It does not appear to be a means of exchange and it is certainly not a store of value. I am delighted the Deputy did not attach the word "currency" to crypto because I think this gives a misleading view of it. I only use the word "crypto". That unbacked currency has no social value whatsoever. Trying to ban it is probably unrealistic and may have unintended consequences. People who put their money in unbacked crypto, and probably the most significant stock of crypto out there is unbacked, are essentially gambling.
  • As you move along the spectrum, you get into backed crypto, which also goes under the name of stablecoin, but which has not proved to be particularly stable at the moment.
  • New EU legislation is coming in this year. The Markets in Crypto-Assets, MiCA, regulation will give us regulatory powers but it will not deal with unbacked crypto. It will deal with stablecoin.
  • I would be grateful if customers could be warned in a very effective way as to the blatant risks of getting involved in crypto currencies in stark red letters.
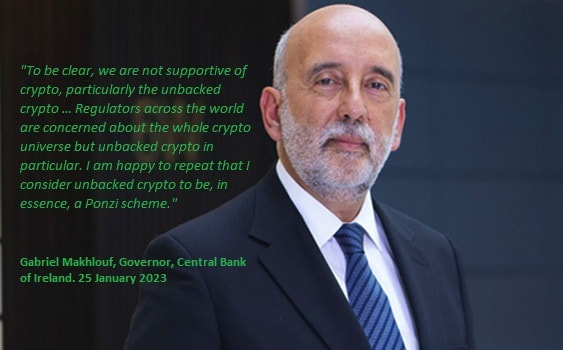
  • To be clear, we are not supportive of crypto, particularly the unbacked crypto … Regulators across the world are concerned about the whole crypto universe but unbacked crypto in particular. I am happy to repeat that I consider unbacked crypto to be, in essence, a Ponzi scheme.
  • The risks, especially with unbacked crypto right now, arise primarily with retail customers. We are not ignoring the fact that financial stability risks could arise in the future.
​You can make up your own mind on Governor Makhlouf thinking on crypto, and by extension the CBI’s position on same.

The UK FCA’s recent communication to overseas crypto industry – 5 April 2023​

Picture
On 5 April 2023, the UK FCA issued a letter to cryptoasset firms that market to UK consumers, including those based overseas to be aware that they will need to comply with the new UK financial promotions regime.  Set out in bold typeface the FCA warns the crypto industry that “The new UK financial promotions regime will apply to all firms making financial promotions of qualifying cryptoassets to UK consumers regardless of whether the firm is based overseas.”.  The letter issued by the FCA’s Val Smith (Head of Payments & Digital Assets, Authorisations) also reminded readers that financial promotions not falling under one of four permitted routes is a criminal offence punishable by up to 2 years imprisonment and/or a fine.  In the letter, the FCA reminded cryptoasset applicants that prior to submitting a registration application, they must ensure that they have provided all of the information requested in the application form.  The FCA also informed that in the two weeks following the 5 April letter, it will send cryptoasset firms a short on-line survey with questions about these firms’ UK businesses and their plans in response to the UK’s new financial promotions regime.  It looks like it will remain a busy time for cryptoasset and virtual asset services firms on the continent of Europe for the rest of 2023.
​
Enjoyed the article? Then please reach out to the Authors at their contact details below.

​About the Authors:

Susan O’Neill – CEO and Co-Founder of SuLu Solutions. Susan is a qualified accountant who has a wealth of expertise having held several senior management positions. SuLu solutions specialise in providing Fintechs with innovative digital asset strategy solutions that can help them stay ahead of the curve. Email [email protected].  Susan is on the Fintech Ireland Advisory Council.

Peter Oakes – Founder of Fintech Ireland and Fintech UK.  Peter is a board director of regulated MiFID, Emoney and Payments companies, and is an advisor to fintech and digital asset firms through international law firm Armstrong Teasdale and his specialist advisory business, CompliReg.  Email [email protected]
0 Comments

Virtual Asset Service Provider applicants told to improve the quality of their applications and  AML/CFT frameworks and knowledge by the Central Bank of Ireland CLICK HERE

11/7/2022

0 Comments

 
Picture
Today (Monday 11 July 2022) the Central Bank of Ireland issued a press release highlighting weaknesses in Virtual Asset Service Providers’ (VASP) AML/CFT Frameworks.

Accompanying today's press release is 
a bulletin in relation to VASPs, seeking to assist applicant firms to strengthen both their applications for registration and their Anti-Money Laundering and Countering the Financing of Terrorism (AML/CFT) Frameworks.

The Central Bank says 
while it seeks to anticipate and support innovation in the financial services industry, firms operating in novel areas must ensure their businesses will not be used to launder the proceeds of crime or to finance terrorism.  The Central Bank issued the bulletin to VASPs to assist them in strengthening their applications and frameworks.

Read more here, including an analysis by CompliReg.
0 Comments

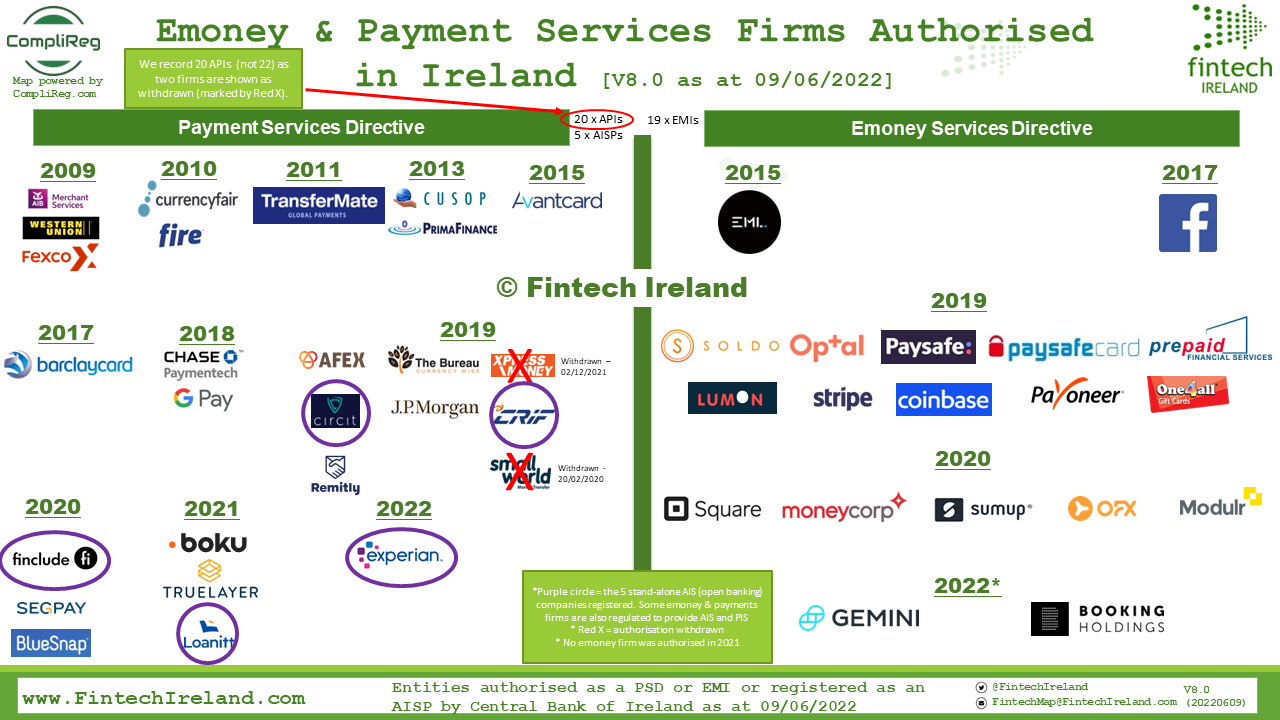
Experian Ireland registered to provide account information services (and updated Regulated Fintech Map v8.0)

9/6/2022

0 Comments

 
Picture
Click for larger image
If you need assistance with an emoney or payments authorisation or an account information service provider registration application, check out Fintech Ireland and CompliReg's handy authorisation guides at https://fintechireland.com/fintech-authorisations.html.
On 9 June 2022 the Central Bank of Ireland registered Experian Ireland Limited as an account information services provider (AISP). Experian Ireland becomes the 5th standalone account information services provider joining Circit Limited (registered 25 February 2019), CRIF RealTime Ireland Limited (registered 30 May 2019), Verge Capital Limited (registered 9 March 2020) and LoanITT Limited (registered 5 November 2021).

Thus far in 2022, the Central Bank of Ireland has only authorised two emoney firms and registered one AISP.  So far no payment services firm has been authorised in Ireland in 2022 as we enter the second half of the year.

Experian Ireland was incorporated in Ireland since 1997. According to CRO filings, the company's turnover for the year ended March 2021 was € 3.71mn up from €5.4mn, recording a loss of €111,000 against a profit in the previous year of $1.34mn.

The register reflects that as at 30 June 2022, the doesn't presently passport services across the European Union. 

As at 30 June 2022, Ireland is now home to 19 authorised electronic money institutions, 20 authorised payment institutions and 5 standalone account information service providers. We have updated our regulated fintech Map to version 8.0 where we showcase these firms.

Our Peter Oakes spoke with Charlie Taylor of the Business Post on Sunday 3 July 2022 about the registration of Experian Ireland as an AISP:
  • "The news was also welcomed by Peter Oakes, a former Central Bank enforcement director and founder of Fintech Ireland, an industry group."Irish customers will be able to share transactional information from their bank account with other banks and third parties. Customers will be able to better monitor, control and improve the way their banking data is used, including managing their so-called ‘credit score’ when looking for financing.
  • “We are yet to see the fruits of open banking in Ireland to the same degree as elsewhere. Together with other fintechs providing open banking, Irish consumers and small businesses will enjoy more choice in an increasingly competitive landscape," Oakes said.

Further Reading: See also Charlie Taylor's article on the authorisation of emoney and payment services firms and the issues firms are facing getting authorised in Ireland in his article of 10 April 2022 titled Defensive attitude of Central Bank putting off fintech investors.  And see our News posts of:
  • 25 April 2022 on the announcement of Bookings Holding becoming an authorised emoney firm; and 
  • 10 April 2022 titled Defensive attitude of Central Bank putting off fintech investors.
0 Comments

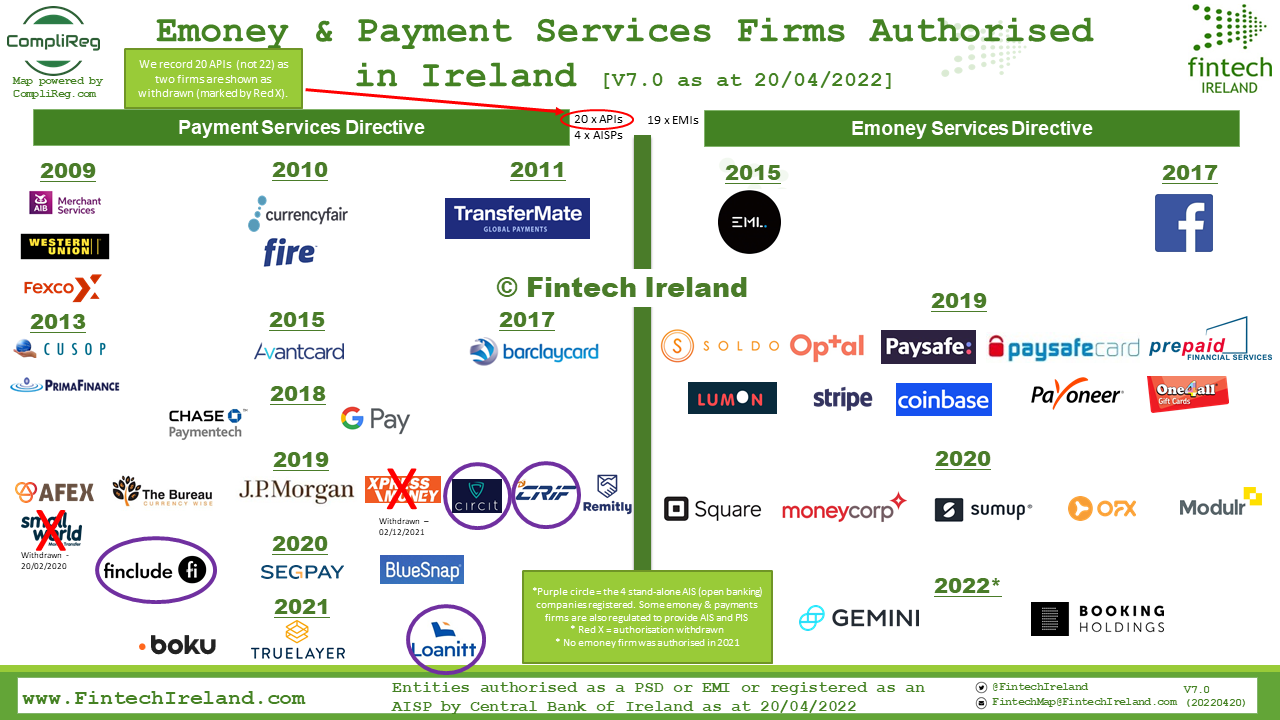
Booking Holdings authorised to provide e-money and payment services (and updated Regulated Fintech Map v7.0)

25/4/2022

0 Comments

 
Picture
If you need assistance with an emoney or payments authorisation or an account information service provider registration application, check out Fintech Ireland and CompliReg's handy authorisation guides at https://fintechireland.com/fintech-authorisations.html
On 20 April 2022 (Central Bank of Ireland run date 21 April 2022), the Irish regulator authorised Booking Holdings Financial Services International Limited as an electronic money institution.  The authorisation comes 21 months following its incorporation on 17 July 2020.

The company, in addition to emoney, is authorised to provide payment services 3b, 3c and 5.  These allow the company to:

*  (3) Execution of payment transactions, including transfers of funds on a payment account with the user’s payment service provider or with another payment service provider:
  • 3 (b) Execution of payment transactions through a payment card or a similar device;
  • 3 (c) Execution of credit transfers, including standing orders
*  5. Issuing of payment instruments and/or acquiring of payment transactions

Ireland is now home to 19 authorised electronic money institutions, 20 authorised payment institutions and 4 standalone account information service providers. We have updated our regulated fintech Map to version 7.0 where we showcase these firms.

Our Peter Oakes spoke with Charlie Taylor of the Sunday Business Post on the authorisation of emoney and payment services firms and the issues firms were facing getting authorised in Ireland.  See Charlie's article of 10 April 2022 titled Defensive attitude of Central Bank putting off fintech investors.


In the article Peter Oakes said:
  • ​Speaking to the Business Post, Peter Oakes, a former Central Bank enforcement director and founder of Fintech Ireland, an industry group, said some companies which had sought authorisation through the Irish regulator had found it difficult to deal with.
  • “The Central Bank is at times coming across as unnecessarily defensive and surprisingly unprepared for meetings with applicants. Wrong or right, this is a situation which has developed and one the regulator is not sufficiently in front of,” he said.
  • Oakes suggested that radical changes were not required to right the current situation.
    “A handful of straightforward enhancements should not only solidify the regulator’s objectives but create a better-informed industry. At the very least it would make clear whether Ireland is a ‘go-to’ effective regulatory jurisdiction for innovation and should prevent the state scoring an own goal by losing out on quality firms moving here because of the current situation,” he said.
    The Central Bank admitted in a statement that authorisation could take time, but said operating a robust authorisation process was “solely aimed at protecting consumers and investors”.

A trawl through the minutes of the Central Bank of Ireland's Commission minutes makes for interesting reading on this topic.  

On 7 December 2021 (not published until 8 February 2022), the record of minutes noted that:
  • [Central Bank's Ed Sibley] a sizeable pipeline of change across multiple sectors, including authorisation activity, such as a high volume of Payment Institution/E-Money Institution authorisations. Work continued with applicant institutions on improving the quality of submissions.  in particular with regard to risk and compliance frameworks.
  • One member asked if there were any particular trends emerging concerning authorisations.
  • Mr Sibley responded that there continues to be very significant change across many sectors. For banking specifically there was a significant growth in international banking sector here because of Brexit, with very significant growth in size, complexity and levels of employment.
  • [Central Bank's Derville Rowland added that] "She also noted the establishment of a new type of entity, virtual asset service providers (VASPs), which were now required to register with the Bank for the purposes of anti-money laundering (AML)​."  

​On 1 March 2022 (not published until 19 April 2022, the day before Bookings Holding was authorised), a partially omitted record of minutes dealing with the Authorisation Process (involving Mary Elizabeth McMunn and Colm Kincaid) was released, the published minutes noted that:
  • Pipeline levels have remained consistently high and not all applications convert to supervised firms.
  • the Bank substantially meets its published service standards across the various sectors.
  • Reprioritisation of supervisory resources into authorisation work has been a key response to authorisation challenges; however, this is not without risk. 
  • Queries were raised in relation to some external impressions that securing authorisation in Ireland can be more onerous than other jurisdictions, and whether there was benchmarking undertaken. Other queries focused on whether post-Brexit authorisation applications had peaked and on the Bank’s engagement with advisors to applicant firms and challenges with ensuring relevant board level oversight within newly authorised entities.
  • ​In response, it was noted that the Bank applies EU standards and norms to its authorisation process, but was seeking to be forward looking in its approach; it wanted resilient firms that can cope with changing circumstances, and that is the robustness of the approach that is taken. It was noted that there was a strong drive at EU level to have rigorous authorisation processes and a strong drive for substance. In relation to the number of applicants, this was not expected to fall off and would in all likelihood increase. While there were levels of engagement with advisors, it was essential to get to the institutions themselves. Early engagement with some of the firms at expression of interest stage was showing a stronger understanding of the Bank’s expectations. In terms of board representation, this was a real and genuine challenge and it was a wider challenge for the State to make sure the expertise is there.
  • The Commission noted the update and agreed to keep under consideration how best to support this work.

Visit our Fintech Ireland Maps page for more information about the fintech and regtech companies we map.

Other Reading:

1) Irish Times Article 20 March 2022: 
https://www.irishtimes.com/business/financial-services/winklesvoss-twins-secure-irish-e-money-licence-for-gemini-payments-1.4831606
2) Linkedin Post 20 March 2022: https://www.linkedin.com/posts/peteroakes_paymentservices-facebook-cryptoasset-activity-6911588283806277632-GaM0
0 Comments

First Irish Funds to invest in CRYPTOASSETS

15/4/2022

0 Comments

 
Picture
This blog is a copy and paste of the CompliReg blog located here -

​This material first appeared on Linkedin here 
​This blog by Peter Oakes, Founder of Fintech Ireland and CompliReg.  Peter qualified as a lawyer in Australia, the UK and Ireland.  He is a director of a number of regulated innovative fintech and adviser to fintech and crypto firms and their professional service providers. Contact him here and follow him on Linkedin and Twitter (Fintech Ireland Twitter).
 

The first Irish regulated funds to take exposure to crypto-assets have been approved by the Central Bank of Ireland (CBI).

The funds, both Qualifying Investor AIFs (QIAIF), will obtain indirect exposure to Bitcoin, by acquiring cash-settled Bitcoin Futures traded on the Chicago Mercantile Exchange (CME). Before you get too excited looking to by some of the digital asset via the QIAIFs note that this channel of exposure is RESTRICTED TO PROFESSIONAL INVESTORS. [NB: As recently as March 2022 the the Central Bank has issued a warning on the risks of investing in crypto assets].  We have provided further details about the regulatory crypto investing landscape in Ireland under 'Further Reading' below.
 
Last month the CBI informed industry bodies that it had approved in principle at least one QIAIF with a low level of exposure to cash settled Bitcoin futures traded on the CME.
 
The two unnamed QIAIFs are the first type of such funds to provide indirect crypto exposure and approved by the CBI.
 
If you want your existing QIAIFs or you wish to establish a new QIAIF to obtain exposure to crypto assets, get in touch (details above).  I am asked on a regular basis by institutional investors and professional investors how they can get exposure to cryptocurrencies and other digitalassets via regulated products. Unless you are able to gain direct exposure via a virtual asset service provider (VASP), the Irish QIAIF model (non-UCITS) might be your avenue. Note however that the CBI has said it is highly unlikely to approve a UCITS proposing any exposure (either direct or indirect) to crypto assets. Thus retail investors wanting crypto exposure in Ireland need to turn to VASPs/Exchanges direct.

Through Fintech Ireland, CompliReg and the industry experts network, we know the lawyers, ManCos and depositories / custodians who can assist institutional/professional firms and funds promoters looking to gain exposure to the crypto markets.  Further, if you are seeking a registration as a virtual service asset provider or authorisation as a MiFID, emoney institution or payments institution to provide services to  institutional, professional and retail clients, check out our Authorisation Page.


Further reading:
  • ID1145 - Central Bank of Ireland 44th Edition (20 December 2021) of the Central Bank AIFMD Q&A

​Question. Can a RIAIF or a QIAIF invest either directly or indirectly in crypto-assets?

Answer. Crypto-assets are generally considered to be private digital assets that depend primarily on cryptography and distributed ledger or similar technology. However, the nature and characteristics of crypto-assets vary considerably. For example, crypto-assets that are tokenised traditional assets (whose value is linked to an underlying traditional asset or a pool of traditional assets (such as financial instruments or commodities)) may have a different risk profile when compared to other crypto-assets that are based on an intangible or non-traditional underlying. For the purposes of this Q&A “crypto-asset” is used to refer to the latter type of crypto-asset. The Central Bank must be satisfied that direct or indirect exposure to crypto-assets is capable of being appropriately risk managed. As of the date of publication of this Q&A, the Central Bank has not seen information which would satisfy it that direct or indirect exposure to crypto-assets is capable of being appropriately risk managed. Though crypto-assets do not all have uniform characteristics, the Central Bank has noted that they can present significant risks, including liquidity risk; credit risk; market risk; operational risk (including fraud and cyber risks); money laundering / terrorist financing risk; and legal and reputation risks. Taking into account the specific risks attached to crypto-assets and the potential that retail investors will not be able to appropriately assess the risks of making an investment in a fund which gives such exposures, the Central Bank is highly unlikely to approve a RIAIF proposing any exposure (either direct or indirect) to crypto assets. In the case of a QIAIF seeking to gain exposure to crypto-assets, the relevant QIAIF would need to make a submission to the Central Bank outlining how the risks associated with such exposures could be managed effectively by the AIFM. The Central Bank’s approach in relation to crypto-assets will be kept under review, continue to be informed by European regulatory discussions on the topic and may change should new information or developments emerge in the future
. 
​

  • ​​ID 1100  - Central Bank of Ireland 36th edition (20 December 2021) of the Central Bank UCITS Q&A

​Question.  Can a UCITS invest either directly or indirectly in crypto-assets?

Answer. Crypto-assets are generally considered to be private digital assets that depend primarily on cryptography and distributed ledger or similar technology. However, the nature and characteristics of crypto-assets vary considerably. For example, crypto-assets that are tokenised traditional assets (whose value is linked to an underlying traditional asset or a pool of traditional assets (such as financial instruments or commodities)) may have a different risk profile when compared to other crypto-assets that are based on an intangible or non-traditional underlying. For the purposes of this Q&A “crypto-asset” is used to refer to the latter type of crypto-asset. The Central Bank must be satisfied that assets in which a UCITS invests are capable of meeting the eligible asset criteria for UCITS and that indirect exposure to the assets is capable of being appropriately risk managed. As of the date of publication of this Q&A, the Central Bank has not seen information which would satisfy it that crypto-assets are capable of meeting the eligible asset criteria for UCITS or that indirect exposure to crypto-assets is capable of being appropriately risk managed. Though crypto-assets do not all have uniform characteristics, the Central Bank has noted that they can present significant risks, including liquidity risk; credit risk; market risk; operational risk (including fraud and cyber risks); money laundering / terrorist financing risk; and legal and reputation risks. Taking into account the specific risks attached to crypto-assets and the potential that retail investors will not be able to appropriately assess the risks of making an investment in a fund which gives such exposures, the Central Bank is highly unlikely to approve a UCITS proposing any exposure (either direct or indirect) to crypto assets. The Central Bank’s approach in relation to crypto-assets will be kept under review, continue to be informed by European regulatory discussions on the topic and may change should new information or developments emerge in the future. 


  • Central Bank of Ireland Warning (22 March 2022)
The Central Bank again emphasised that crypto assets are highly risky and speculative, and may not be suitable for retail customers. In particular people need to be alert to the risks of misleading advertisements, particularly on social media, where influencers are being paid to advertise crypto assets.  The Central Bank has published a plain English explainer for consumers on cryptocurrencies.

  • European Supervisory Authorities (EBA, ESMA and EIOPA Warning (17 March 2022)
The ESAs warned consumers that many crypto-assets are highly risky and speculative. The ESAs set out key steps consumers can take to ensure they make informed decisions.
0 Comments
<<Previous
Forward>>

    Author

    Fintech Ireland

    Archives

    December 2026
    September 2026
    June 2026
    May 2026
    March 2026
    December 2025
    October 2025
    September 2025
    July 2025
    March 2025
    February 2025
    January 2025
    December 2024
    November 2024
    October 2024
    July 2024
    June 2024
    May 2024
    April 2024
    March 2024
    February 2024
    December 2023
    November 2023
    October 2023
    September 2023
    August 2023
    July 2023
    June 2023
    May 2023
    April 2023
    February 2023
    October 2022
    July 2022
    June 2022
    April 2022
    March 2022
    January 2022
    December 2021
    July 2021
    May 2021
    April 2021
    March 2021
    February 2021
    January 2021
    November 2020
    October 2020
    September 2020
    August 2020
    July 2020
    April 2020
    February 2020
    July 2019
    April 2019
    March 2019
    February 2019
    January 2019
    October 2018
    September 2018
    July 2018
    June 2018
    May 2018
    April 2018
    March 2018
    January 2018
    October 2017
    September 2017
    August 2017
    July 2017
    June 2017
    May 2017
    March 2017
    January 2017
    December 2016
    November 2016
    September 2016
    August 2016
    July 2016
    June 2016
    May 2016
    April 2016
    March 2016
    February 2016
    December 2015
    September 2015
    July 2015
    June 2015
    May 2015
    April 2015
    March 2015
    September 2014
    January 2014

    Categories

    All
    Account Information Services
    AISP
    Anne Boden
    Authorisations
    #bankinginquiry
    Bank Of England
    Bitcoin
    Brian Fahey
    British Embassy Dublin
    Business Post
    CB Insights
    Central Bank Of Ireland
    Challenger Bank
    Chambers And Partners
    Competition And Consumer Protection Commission
    Compliance
    Consultations
    Contributor Articles
    Corporate Governance
    Crowdingfunding
    Crypto Assets
    Cryptocurrencies
    Currency Fair
    Cyber Security
    DeFi
    Department Of Finance
    Digital Assets
    Digital Euro
    Digital Wallets
    Directors Duties
    Disruption
    Dogpatch Labs
    Electronic Money
    EML Payments
    EMoney
    European Commission
    Financial Literacy
    Fintech
    Fintech Abu Dhabi
    Fintech Hub
    Fintech Ireland
    Fintech Ireland Map
    Fintech Ireland Summit
    Fintech Leaders Series
    Funding
    Funds
    Gemini
    Ifs2020
    Ifsc
    Innovation
    International Financial Services Strategy
    Ireland For Finance
    Irish Fintech Companies
    John Berrigan
    Kraken
    Mairead McGuiness
    Marketplace
    MiCA
    Mifid
    Moneycorp
    Money Laundering
    Monzo Bank
    MoonPay
    MyComplianceOffice
    Neobanks
    Newsletter
    Nuapay
    @oakeslaw
    OFX Payments
    Paschal Donohue
    Payments
    Payments Institution
    Paysafe
    Payward
    Peer To Peer
    Peer-to-peer
    Realex Payments
    Regtech
    Regulated Fintech
    Regulation
    Roboadvisers
    Robo Advisors
    Robo-advisors
    Ronan Gallagher
    RTE
    Sandbox
    Sentenial
    Simon Harris
    Square
    SquareUp International
    Stablecoins
    Starling Bank
    Strategy
    SYNC Payments
    The Project Foundry
    TransferMate
    Unicorn
    Unicorns
    USA Today
    Virtual Assets
    Wealthtech
    Zodia Custody
    Zodia Markets

©Fintech Ireland and ©Fintech.  Fintech Ireland (523657) and Fintech (523656) are registered with the Companies Registration Office in Ireland
www.fintechireland.com / www.fintechireland.ie / www.irishfintech.ie / www.irishfintech.com / www.fintechcareers.ie
Privacy Policy